Loan Programs ·
HomeStyle Renovation Loans: Buy the Home, Fund the Fixes
Mack Humphrey, CMPS
Certified Mortgage Planning Specialist · NMLS #1110618
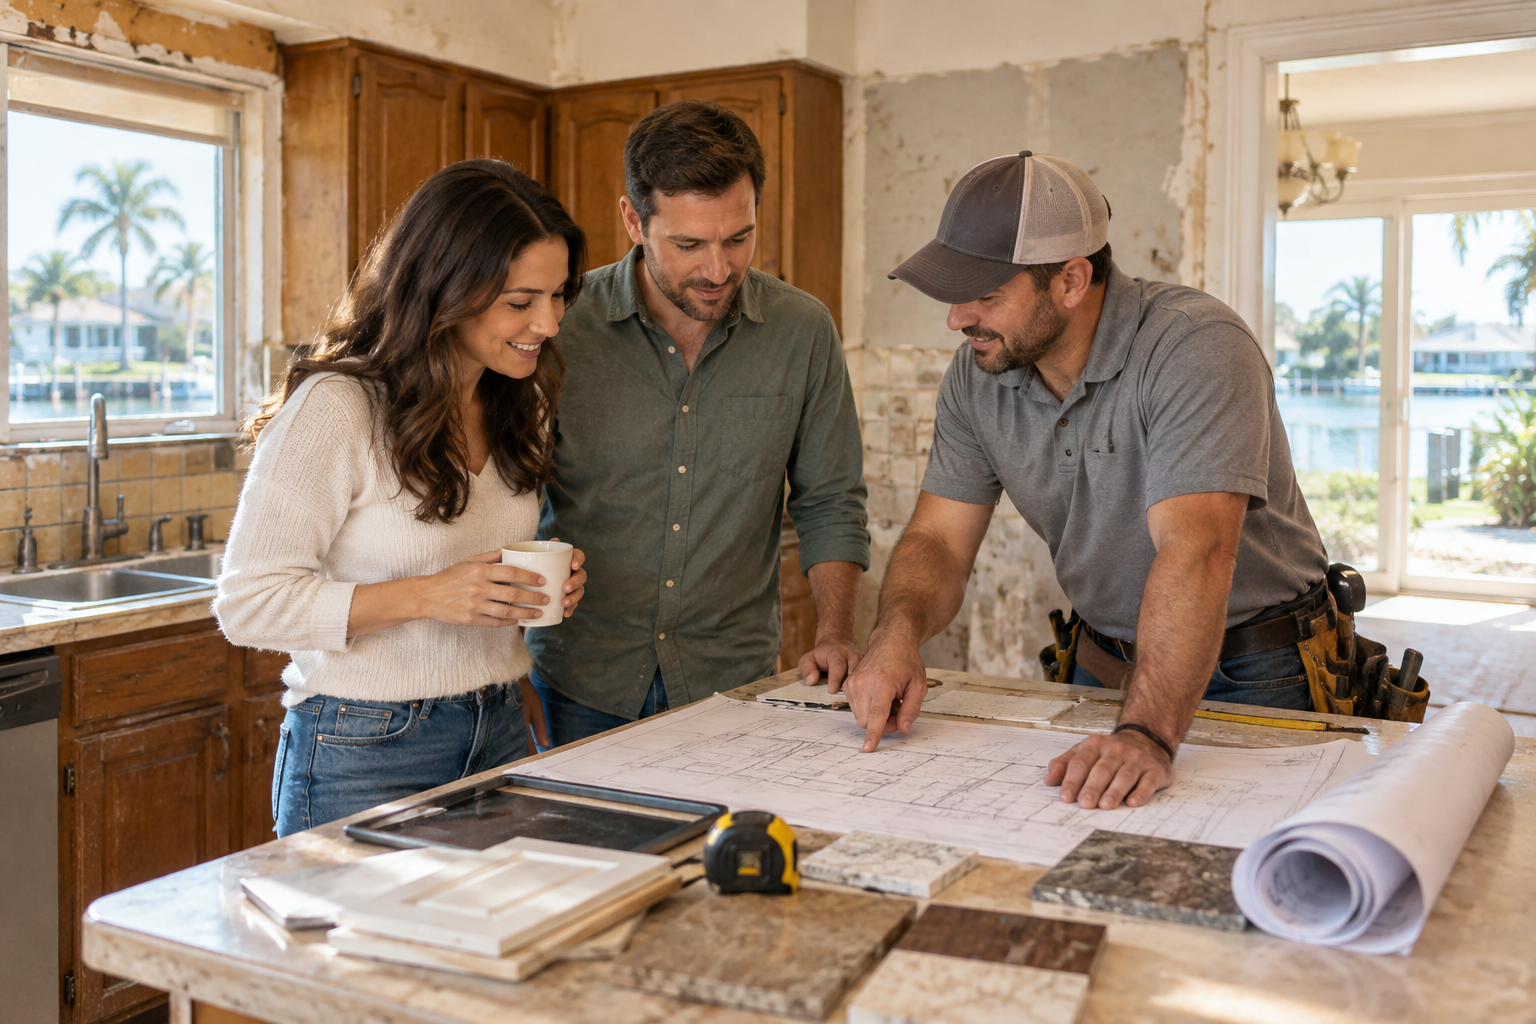
Sometimes the right house has the wrong kitchen. Or the location is perfect, but the roof, flooring, and bathrooms all need attention.
That creates a common problem: You may be able to handle the mortgage payment, but buying the house and paying for improvements out of pocket feels like too much at once.
One option I like to explain is the HomeStyle Renovation loan, a conventional mortgage feature from Fannie Mae. It can combine a home purchase and eligible improvements in one loan. But it takes more planning than a standard purchase mortgage—and understanding that difference matters before you make an offer.
How a HomeStyle Renovation Loan Works
With a typical purchase mortgage, you finance the home in its current condition. Major improvements usually become a separate project with a separate funding source after closing.
A HomeStyle Renovation loan brings approved renovation costs into the mortgage from the start. The lender reviews both your finances and the proposed project. An appraiser then evaluates the property based on its expected condition after the approved work is complete.
That as-completed value is central to the program. It helps the lender evaluate the home you are creating, rather than looking only at the home you see during the showing.
Here is the basic structure:
- You choose a property and define the improvements.
- A contractor provides a detailed scope of work and pricing.
- The lender reviews the project, appraisal, and mortgage application.
- At closing, renovation funds are placed in a controlled account.
- Funds are released through an approved process as work progresses.
You do not receive an unrestricted check to remodel however you want. The work, budget, and funding process are part of the mortgage approval.
Homeowners can also explore HomeStyle through a refinance, although that means evaluating the replacement mortgage—not just the renovation budget.
What Improvements Can It Cover?
HomeStyle can support a broad range of improvements that are permanently attached to the property and meet program and lender requirements. It is not limited to fixing safety problems or replacing broken equipment.
Depending on the property and approved project, eligible work may include:
- Kitchen and bathroom remodeling.
- Roof replacement and window upgrades.
- Heating, cooling, plumbing, or electrical improvements.
- Flooring and other permanent interior updates.
- Accessibility changes that make daily living easier.
- Certain additions or more extensive improvements.
That flexibility does not make every project a fit. A home that needs extensive reconstruction requires a very different review from one that needs cabinets and flooring. Property condition, structural plans, permits, and the ability to finish on schedule all matter.
Here in Northeast Florida, I would also pay close attention to roof condition, moisture damage, and insurance eligibility. Financing a repair does not automatically solve an insurance problem. The lender and insurance provider need to understand the property’s condition and the planned work early.
I also remind buyers that renovation cost and added value are not the same thing. A beautiful custom kitchen may cost more than the value it contributes to the appraisal.
The Contractor and Timeline Are Part of the Loan
The biggest surprise for many buyers is how much must happen before closing.
On a standard purchase, you might collect remodeling ideas after getting the keys. With HomeStyle, the lender generally needs a clear project plan before the loan can close. That means involving contractors while you are still buying the home.
I encourage buyers to work through these steps early:
- Choose a contractor who can handle the paperwork. The lender may review licensing, insurance, experience, and financial capacity.
- Get a detailed bid. “Remodel the bathroom” is not enough. The scope should identify materials, labor, and specific tasks.
- Identify permit needs. Ask the contractor and local building department what the work requires.
- Understand the draw process. Contractors need to know when payments can be released and what inspections or documentation are required.
- Build a realistic schedule. Material delays and contractor availability do not disappear because the work is mortgage-financed.
Do not assume you can perform the work yourself or start demolition before closing. Program rules and lender policies govern who can do the work and when it can begin.
After closing, the project must stay within the approved requirements and completion timeline. Changes may require lender approval, especially if they affect cost or scope.
This is why I would rather have the contractor conversation before you commit to a tight purchase deadline. The mortgage, purchase contract, and renovation schedule need to work together.
What to Know About Qualifying and Costs
HomeStyle is a conventional mortgage, not a renovation grant. You still need to qualify based on factors such as credit, income, debts, and available funds. The property and renovation plan must qualify, too.
Not every lender offers this feature, and participating lenders may have additional requirements. A standard conventional preapproval does not necessarily mean a renovation loan is ready to go.
The budget also includes more than the contractor’s headline price. Depending on the project and lender, you may need to account for:
- Permits, inspections, and project-related fees.
- A contingency reserve for unexpected work.
- Required cash at closing and any financial reserves.
- Temporary housing or storage if you cannot live in the home.
- Expenses that are not eligible to be financed.
A contingency reserve is especially important in an older house. Opening a wall can reveal plumbing or wiring issues that were not visible during a showing.
You should also plan for mortgage payments while renovations are underway. Do not assume payments wait until you move in or that temporary housing costs will be covered.
Finally, financing improvements over a long mortgage term means paying interest on those improvements. A manageable monthly payment is useful, but it is not the same as the lowest total project cost.
When This Loan Is Worth a Closer Look
I see HomeStyle as a planning tool, not a shortcut around an expensive house.
It may be worth exploring when you have found a home in a location you want, the needed changes are clearly defined, and a qualified contractor can complete them within the lender’s requirements. It can also help when paying cash for improvements would leave you with too little financial breathing room.
It may be less appealing when you need a very fast closing, the work is mostly cosmetic and affordable out of pocket, or the project depends on uncertain permits and an open-ended scope.
Before recommending a direction, I would compare the full picture: purchase price, renovation costs, cash needed, monthly payment, insurance, and a realistic backup plan. I would also compare it with buying a move-in-ready home or using a different renovation financing approach.
The question is not simply, “Can we finance the remodel?” It is, “Does the finished home make sense for your budget and your life?”
Let's Talk
Considering a house that needs work? Call me, Mack Humphrey, at (720) 771-1308, or reach out to the Mack Humphrey Mortgage Team at First Coast Mortgage Alliance. We can have a no-pressure conversation about the property, your renovation plans, and whether this loan deserves a closer look.
Talk to Mack
Have questions about your own situation? Let's run your numbers together, with no pressure and no obligation.