Homeownership ·
Build a Home Repair Budget Before Something Breaks
Mack Humphrey, CMPS
Certified Mortgage Planning Specialist · NMLS #1110618
Your Mortgage Payment Is Only Part of the Plan
A house can fit comfortably into your monthly budget and still deliver an uncomfortable surprise. The air conditioner quits. A small plumbing leak turns into a cabinet repair. A roofer says that another patch may not be the best use of your money.
As a mortgage planner, I want homeowners to have room for these expenses—not just room for their mortgage payment. Owning a home should not mean starting a financial scramble every time something wears out.
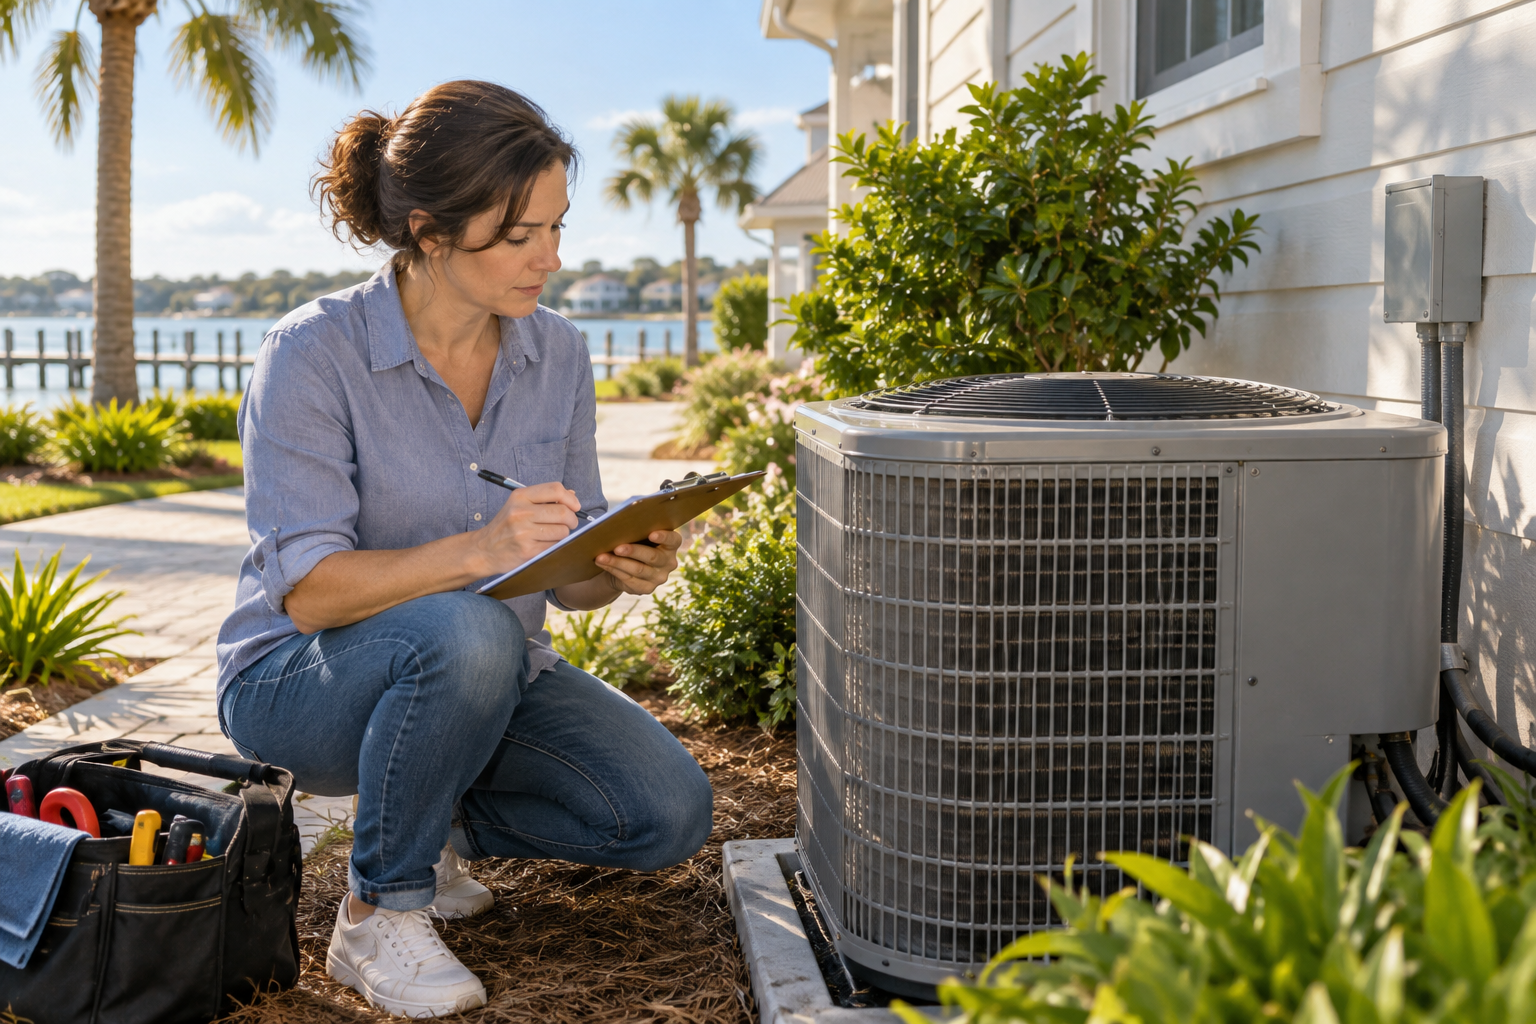
Here in Northeast Florida, heat, humidity, heavy rain, and coastal conditions can put extra demands on a house. That makes a repair plan especially valuable. But you do not need to predict every problem or become a building expert.
You need a basic picture of your home's condition, a way to rank upcoming work, and a savings plan that reflects the house you actually own.
Start With Your Home's Condition, Not a Rule of Thumb
You may have heard that homeowners should save a fixed share of their home's value for maintenance. That can be a starting point, but it misses something important: your market value does not tell you how close your equipment is to wearing out.
Two homes with similar values can have very different needs. One may have a newer roof and recently replaced appliances. The other may have several major systems approaching replacement together.
I recommend making a simple home condition list. A notebook or spreadsheet is enough. Include:
- Roof and gutters, if applicable
- Heating and cooling equipment
- Water heater and accessible plumbing
- Electrical system
- Windows, exterior doors, and weather seals
- Exterior paint, siding, and exposed wood
- Major appliances
- Drainage, irrigation, and other property-specific equipment
For each item, record its approximate age, known problems, last service date, and available warranty information. If you do not know the age, look for receipts, equipment labels, permit records, or information from your purchase inspection.
Then separate what you know from what you are guessing. An older system is not automatically failing, and a newer one is not automatically trouble-free. A qualified professional can help you understand its condition and whether maintenance, repair, or replacement makes sense.
If you own a condo or a home in an association, check which components are your responsibility. Do not assume the association covers something simply because it is outside your living space.
Give Every Project a Priority and a Time Window
Once you have your list, resist the urge to treat everything as equally urgent. A worn countertop and an active roof leak belong in very different categories.
I like to organize home spending into three groups:
Protect the people and the property. These are safety concerns or problems that can cause further damage. An active leak, a suspected electrical hazard, or a failing structural component needs prompt professional attention. If something presents an immediate danger, address safety first rather than waiting for your budget review.
Maintain and prepare. This includes routine service and aging components that still work but deserve a plan. Think air-conditioning maintenance, exterior sealing, or a water heater that a plumber recommends watching closely.
Improve when the budget allows. Cosmetic updates and convenience upgrades usually offer more flexibility. New finishes may be appealing, but they should not quietly consume the money set aside for a necessary repair.
Next, give each item a rough time window: act now, plan for the coming year, or monitor for later. Treat these as planning notes, not promises about how long equipment will last.
For Florida homeowners, I would also put moisture control on the checklist. Watch for water stains, persistent dampness, deteriorated seals, and drainage that sends water toward the house. Catching the source early may keep a manageable repair from becoming a much larger project.
Turn the List Into a Monthly Savings Habit
A repair list becomes useful when you connect it to your cash flow.
Start with routine costs you can reasonably expect: service visits, filters, pest prevention, and similar upkeep. Add those expected annual expenses together and divide by the months in a year. That gives you a monthly starting point for ordinary maintenance.
For a larger project, use a separate calculation:
Current estimated cost minus money already saved, divided by months until the planned work.
The result is a savings target—not a guarantee that the final bill will match your estimate. Update it when you receive better information.
Keep planned home-repair money separate from everyday spending if that helps you avoid using it for something else. Money needed soon generally belongs somewhere accessible and stable, rather than tied up in something you may have to sell at a loss.
I also distinguish a home-repair fund from a broader emergency fund. A likely appliance replacement and an unexpected loss of income are different risks. One pool of money may end up covering both, but recognize that a major repair can leave you with less protection for everything else.
If your savings target does not fit your budget, that is useful information. Revisit optional projects, ask a professional whether work can be safely phased, and start with what you can sustain. Do not postpone a serious hazard just to stay on schedule financially.
Get Better Estimates Before Choosing How to Pay
You do not need a firm bid for every possible future repair. But when a major project moves closer, replace your rough guess with written estimates.
Compare the scope of work, not just the total. Ask contractors:
- What is included, and what is excluded?
- Are permits or inspections needed, and who handles them?
- Could hidden damage change the price?
- What warranties apply to materials and labor?
- How will changes to the work be approved and documented?
Verify licensing where required and appropriate insurance. For major or unclear contract terms, consider having a qualified attorney review the agreement.
Be careful about assuming homeowners insurance will pay for a worn-out component. Coverage depends on your policy and the cause of damage; routine deterioration is generally different from a covered loss. Ask your insurance professional rather than building your budget around an expected claim payment.
Likewise, home equity is not the same as cash ready to spend. Borrowing against it requires qualification, can involve costs and processing time, and adds debt secured by your home. Contractor financing also deserves a close look at the full repayment terms—not just the advertised payment.
My preference is to discuss those choices before a repair becomes urgent. A savings plan gives you more breathing room to compare options and decide what fits your household.
Let's Talk
If upcoming home repairs are putting pressure on your budget, call me at (720) 771-1308 or reach out for a no-pressure conversation. I'll help you look at how your mortgage fits into the bigger picture.
Mack Humphrey, CMPS, NMLS #1110618
Mack Humphrey Mortgage Team at First Coast Mortgage Alliance
Ponte Vedra Beach, Florida
Talk to Mack
Have questions about your own situation? Let's run your numbers together, with no pressure and no obligation.